Are the earnings real?
Quality of earnings: what the business genuinely earns once one-off items, owner costs, related-party charges and accounting timing are stripped out.
Independent buy-side financial due diligence, investment appraisal and transaction support for private investors, funds and family offices. One senior expert, from the first call to the final report.
Finance experience fromRohlik GroupOrganonJohnson & JohnsonDXC TechnologyAPS Holding
A pitch deck tells a story. The ledgers, the bank statements and the supplier invoices tell you whether it is true.
Most investors already sense what worries them. Our job is to turn that instinct into a number you can act on – or to rule it out with confidence.
Quality of earnings: what the business genuinely earns once one-off items, owner costs, related-party charges and accounting timing are stripped out.
Gross margin rebuilt from landed cost – inbound freight, the discounts customers actually receive, and returns. Not from list prices.
Inventory and its age, receivables and their collectability, debt and guarantees – and whether equity is still positive once everything is recognised.
Related parties, ownership look-through and intercompany pricing: how much of the supply chain and customer base sits inside the family.
Monthly runway at the current burn, the working capital the plan will absorb, and what has to be true for the business to fund itself.
The three-to-five-year case rebuilt as a driver-based model. The two or three assumptions that decide the outcome are isolated and stress-tested.
Findings are tagged by where they came from, and a tag is never upgraded without new evidence. It sounds pedantic – until the moment you are negotiating and someone asks how you know.
In a statement, ledger, register entry, contract or bank line. You can put it in front of the other side.
Management said it. Useful, not yet proof – and flagged wherever it drives a number.
Reconstructed from the data because direct evidence was not provided. The method sits right beside the conclusion.
Requested, not received. Listed at the front of the memo – an unanswered question is often the cheapest information in the report.
Every engagement ends with three documents. The recommendation comes first – on a single page you can hand to whoever decides. Everything behind it is there the moment anyone wants to check a figure.
One page with every answer: the recommendation, the five figures it rests on, the conditions worth negotiating and what would change the conclusion. Written for the person who signs.
The mechanics and the proof. Source data exactly as received, every output a live formula, and a checks tab that must reconcile to zero. Any figure traces back to the file it came from.
The full story for your partners, board or lender – every figure drawn from the workbook – and a walkthrough call where you can challenge any of it.
 Decision memo · illustrative
Growth is real. The margin is not what was presented, and working capital absorbs the cash the business does earn.
| EUR thousand | Claimed | Verified | |
|---|---|---|---|
| Revenue, last 12 months | 12,000 | 9,600 | D |
| Gross margin | 28.0% | 17.5% | I |
| EBITDA | 1,400 | 380 | D |
| Free cash flow | 600 | (520) | D |
You know the scope, the fee and the deadline before any work begins – and where the analysis stands at every point after that.
On the decision in front of you. We establish what the work actually is – and whether it is work we should take on.
A short proposal: the questions, the document request list, the timeline and a fixed fee. The NDA is signed before the first file is opened.
Every figure traced to its source, every finding tagged by the strength of its evidence. You know where the work stands at every point.
The one-page memo, the workbook and a call on what the numbers mean and what to do about them.
A fixed fee or day rate in writing after the first call. Extra days only with your written approval.
Signed before a single file is opened. Client names are never published.
Nothing is earned from the deal going ahead. The answer is the product, not the transaction.
In English or Czech. Within one working day you know whether we can help.
From finance leadership roles in international groups and from independent engagements. Independent client work is confidential and described without identifying details.
Ran the FP&A workstream: built the investor financial model, delivered data and insight directly to investors, coordinated due diligence across legal, commercial and finance with the external advisers, and prepared the CFO's investor presentations.
Built the financial model behind a group bond restructuring and defended it with external stakeholders. Led the crisis cash plan and the group cash-flow forecast behind a bank facility application.
Financial diligence on a cross-border consumer goods group: margin quality, related-party supply and credit risk, cash runway and the three-to-five-year plan behind the investor's decision.
Built the investor financial model for a hospitality group that brought international investors back to the negotiating table.
Monthly model, valuation and payback analysis for a private investor offered equity in a new Prague practice – including the rent and fit-out it can afford.
Redesigned controlling, reporting and cash-collection processes for SMEs, replacing manual Excel with driver-based management reporting.
“The job is to give you the answer – not the one you hoped for.”Tsvetomir Todorov
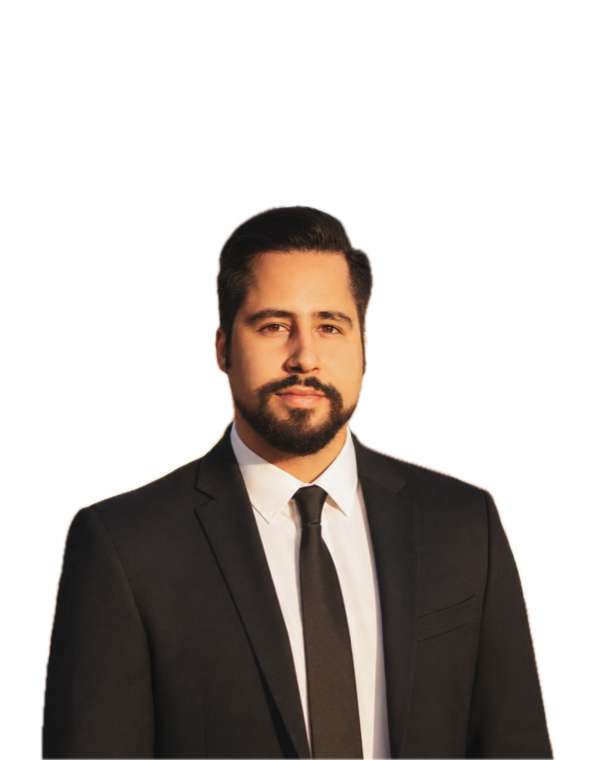
Partner, Financial Services · Strategix
Twelve years in finance across international, multi-entity groups – from group controlling and FP&A to capital raising, restructuring and crisis cash management. At Strategix he leads financial due diligence and advisory, and personally delivers every engagement.
His work starts where investors need certainty: turning ledgers, bank statements and management cases into a clear answer – and standing behind every figure in it.
Direct: tsvetomir@strategix.one · +420 797 972 000
Due diligence is often where the work starts, not where it ends. The same person can take you through valuation, investor readiness and the finance function after you invest.
See the business behind the pitch.
Quality of earnings, real margins, balance sheet and debt, related parties, cash runway
One-page answer, formula-driven workbook, presentation
What your stake is really worth.
Valuation, returns and payback, scenarios, deal structure and protections
Decision memo, investment model, term recommendations
Ready before the first investor meeting.
Investor model, 5-year plan, equity story, data room, diligence Q&A
Investor-grade model and presentation, organised data room
Reporting that runs the business.
Driver-based forecasting, board reporting, 13-week cash flow, cash collection
Working models, reporting pack, documented process
Senior finance without the full-time hire.
Investor and lender reporting, cash governance, budgeting, finance set-up
A senior finance partner for a set number of days per month
Not seeing your question? Write or call – you will have an answer within one working day, in English or Czech.
A fixed fee or a day rate, agreed in writing after the introductory call and before any work starts. Phase one is normally a block of days paid in advance – unused days are refunded, and extra days are added only with your written approval. You will never see an invoice you did not agree to first.
One to three weeks from the point the data is complete. The pace is almost never set by the analysis – it is set by how quickly the target produces its accounts, ledgers and bank statements. That is why the document request list goes out with the proposal, not after it.
The decision you are facing, the deadline and whatever documents you already have. A specific document request list follows with the proposal.
That is a finding in itself, and a common one. The work then shifts to what can be verified independently: public filings, register and insolvency checks, VAT reliability, counterparty confirmations and the internal consistency of what has been provided. You get a clear statement of what could not be tested and what that leaves open.
No. An audit gives a regulated opinion on whether historical statements are fairly presented. Due diligence asks a commercial question: does this business earn what it says it earns, and will it still be solvent after you invest? Neither replaces the other.
Yes. Valuation, returns, payback and deal structure sit under investment appraisal, and the two usually run together: diligence establishes what the numbers really are, appraisal turns them into what your stake is worth and which protections the terms need.
You, and anyone you name. Even if the target company pays the fee, the report belongs to you – and that is written into the engagement terms before work begins.
One senior expert does the work from the first call to the final report – at a fraction of the cost, and without a team of juniors learning on your data. Where a transaction needs a signed regulated opinion, or the scope is genuinely large, a bigger firm is the right answer – and we will tell you so.
If that is what the numbers say, yes. There is no commission and no stake in your decision. The job is to give you the answer – not the one you hoped for.
English, Czech or Bulgarian. Recent work has involved counterparties across Europe, Asia and the Gulf.
No. This is financial analysis and advisory for business decisions – not regulated investment advice on securities, and not tax or legal advice. The analysis supports your decision. The decision stays yours.
A 30-minute introductory call comes first. We agree what the work is before any fee is discussed – and if it is not something we should take on, you will hear that within one working day.
Tsvetomir Todorov · tsvetomir@strategix.one · +420 797 972 000
Strategix financial services are financial analysis and advisory for business decisions. They are not regulated investment, tax or legal advice, and nothing on this site is a recommendation to buy or sell any security.
Tell us what you are facing. We will get back to you within one business day.
Or directly: +420 797 972 000 · tsvetomir@strategix.one